
One of the most significant steps for entrepreneurs whose businesses depend on the use of cars on a daily basis is to secure a small business auto loan. Whether the business involves the delivery of goods, visiting clients, or the transportation of equipment, the availability of financing has a significant impact on the growth of the business. However, not all businesses are treated the same. There are industries that are considered “high risk,” and obtaining a small business auto loan might be difficult.
Industries Most at Risk
- Cannabis Industry: Despite being legalized, cannabis businesses will continue to be strictly federal due to the lack of banking access for them. This can create legal complications that lenders will want to be careful with when considering issuing a small business auto loan.
- Logistics and Trucking Industries: Although trucking companies play an essential role in the economy, they are affected by fuel cost volatility, maintenance costs, and the unpredictable economy, which all affect cash flow. As a result, lenders borrow much more carefully to create a small business auto loan without proper financials.
- Construction Industries: Construction businesses typically have revenues that are dependent on the season, periodic payments for the completion of projects, and the economy. Many new construction companies will find that this uncertainty in their financials will make it difficult to qualify for a small business auto loan.
- Launching Business Enterprises: As a new company, the absence of a credit history or revenue will cause lenders to consider your business a higher risk than an established company. Even though a company may have a proven business model, lenders may not believe that the new company will produce enough revenue to repay the small business auto loan.
- Delivery and Ride Share Services: Typical gig-based businesses rely on 3rd Party platforms such as Uber, Lyft, and food delivery services. These companies find it challenging to rely on their services because of the uncertainty associated with the income produced from their services, causing a negative impact on small business auto loan approvals.
Why Lenders Question These Industries
- Revenue Instability: There are many high-risk industries where revenue is unstable. This is a problem for a small business auto loan.
- Regulatory Concerns: Industries such as the cannabis industry have regulatory challenges. This is a problem for a small business auto loan.
- Asset Depreciation and Usage: Industries such as trucking or construction have high asset depreciation. This is a problem for a small business auto loan.
- Higher Default Rates: Industries have a history of defaulting on loans. This is a problem for a small business auto loan.
Ways to Up Your Odds of Getting Approval
Even if your business is part of a high-risk industry, that alone won’t prevent you from getting a small business auto loan. What it will do is require you to beef up your application.
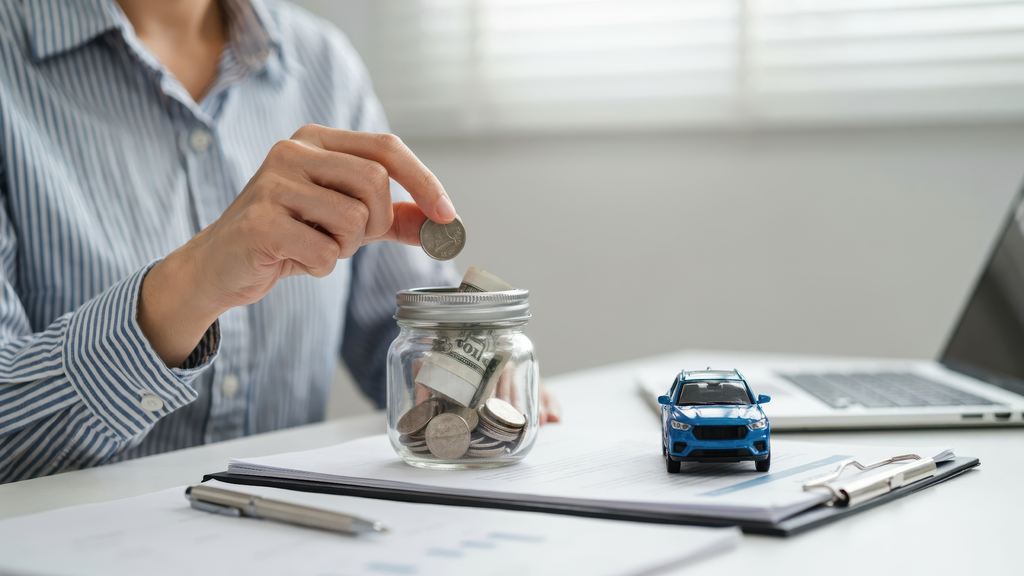
- Boost the Amount of Your Down Payment: You can basically lower the risk that the lender will take by making a bigger payment right from the beginning. This demonstrates your dedication, and at the same time, you end up with a smaller loan amount, which gets you one step closer to getting your small business auto loan approved.
- Use Other Things Besides Your Car as Security: If your business is a high-risk one, putting up assets like your equipment or even a real estate property as collateral can definitely help you get a small business auto loan.
- Keep Credit Records Clean: When it comes to credit scores, both your personal and business credit scores will be assessed. Having a good credit history may compensate for the risks associated with your industry when you apply for a small business auto loan.
- Demonstrate Regular Cash Flow: You can put together your bank statements, invoices, contracts, and so on, which will exhibit your steady earnings. By showing this, you are convincing the lenders that you have the ability to pay back the small business auto loan.
- Pick a Lender Wisely: The way some lenders look at the industry is not the same across the board. There are some that work with high-risk industries, and, therefore, they have the small business auto loan options that are more flexible.
- Gather Thorough Papers: Don’t just focus on getting tax returns. Also, include business licenses and financial projections. The more open you are, the higher your chance of landing a small business auto loan will be.
Conclusion
If you work in a high-risk industry, don’t assume that you’ll automatically be denied a small business auto loan; however, you should expect your lender to scrutinize your financial viability and conduct an assessment of your risk factors before making a decision about whether to issue you a loan. If you improve your credit rating, provide a higher down payment, and offer your lender strong supporting evidence, you can mitigate any obstacles. With proper preparation and strategy, businesses that operate in industries such as trucking, construction, or even cannabis may also qualify for small business auto loans and therefore continue to grow.